If you have outstanding tax penalties, interest or fines relating to periods up to 31 December 2025, there is an important tax relief opportunity you should know about.
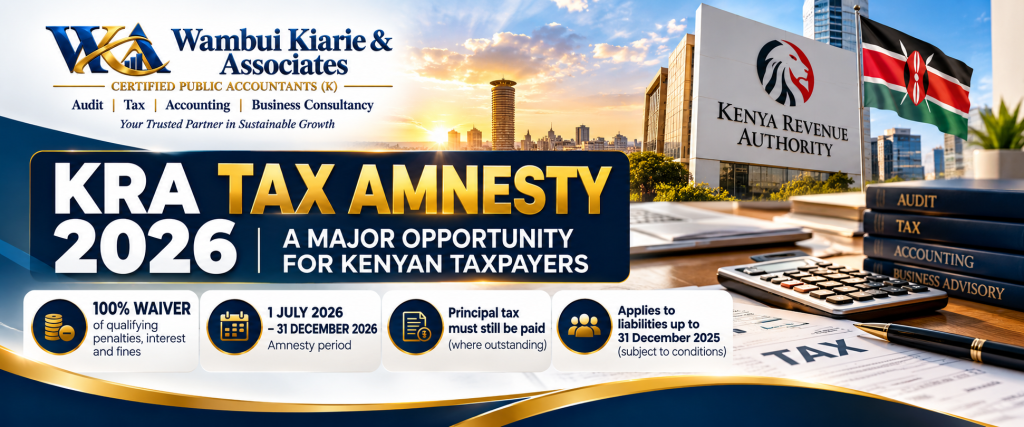
The Kenya Revenue Authority (KRA) Tax Amnesty Programme 2026 is currently in effect and provides for a 100% waiver of qualifying penalties, interest and fines on tax liabilities relating to periods up to 31 December 2025, subject to the conditions set out under the law.
The amnesty commenced on 1 July 2026 and runs until 31 December 2026.
For taxpayers with old tax liabilities, this could provide a significant opportunity to regularise their tax affairs and eliminate qualifying accumulated penalties and interest.
However, there is an important distinction to understand: the amnesty does not waive the principal tax owed.
If you owe principal tax for a qualifying period, that principal amount must be settled in accordance with the amnesty requirements before the related penalties, interest and fines can be waived.
What Is the 2026 KRA Tax Amnesty?
Tax amnesty is a form of tax relief under which qualifying taxpayers may have certain accumulated penalties, interest and fines waived when they meet specified conditions.
Under the 2026 programme, KRA is providing a 100% waiver of qualifying penalties, interest and fines relating to tax liabilities accrued on or before 31 December 2025.
The programme was reintroduced through the Finance Act, 2026, which amended the relevant provisions of the Tax Procedures Act.
The amnesty period is:
1 July 2026 – 31 December 2026
This means taxpayers who may benefit should not wait until the last few days of December to review their tax position.
KRA has specifically encouraged taxpayers to resolve outstanding tax matters and complete the necessary processes before the deadline.
What Exactly Does the Tax Amnesty Waive?
One of the most important things to understand is that the tax amnesty does not cancel the principal tax.
Instead, it applies to qualifying:
- Interest
- Penalties
- Fines
relating to eligible tax liabilities for periods up to 31 December 2025.
For example, imagine a taxpayer has an old tax liability structured as follows:
| Tax liability | Amount |
|---|---|
| Principal tax | KSh 300,000 |
| Interest | KSh 120,000 |
| Penalties | KSh 150,000 |
| Fines | KSh 30,000 |
| Total | KSh 600,000 |
If the liability qualifies under the amnesty and the taxpayer satisfies the applicable conditions, the KSh 300,000 principal tax remains payable, while the qualifying penalties, interest and fines may be waived.
In this example, that could potentially eliminate KSh 300,000 in qualifying additional liabilities.
The exact treatment, however, depends on the taxpayer’s actual KRA ledger and whether the relevant liabilities meet the amnesty conditions.
Who Qualifies for the KRA Tax Amnesty?
There are several situations in which a taxpayer may benefit.
1. You Have No Outstanding Principal Tax
If you have already paid all the principal tax relating to periods up to 31 December 2025 but your KRA iTax ledger still shows qualifying interest, penalties or fines, you may automatically qualify for the amnesty.
According to KRA, no separate application is required in this situation.
The system will process the qualifying waiver and update the taxpayer’s ledger.
This is particularly relevant for taxpayers who previously settled their tax but have continued to see accumulated penalties or interest on their iTax accounts.
2. You Have Outstanding Principal Tax
If you still owe principal tax relating to a period on or before 31 December 2025, you can still potentially benefit from the amnesty.
The key requirement is that the qualifying principal tax must be fully settled by 31 December 2026.
There are two main ways of doing this.
Option A: Pay the Principal Tax in Full
A taxpayer can settle the qualifying principal tax during the amnesty period.
Once the qualifying principal tax has been fully paid, the applicable penalties, interest and fines can be waived in accordance with the programme.
Option B: Use a Structured Payment Plan
Taxpayers who cannot settle the entire principal amount in one payment may apply for an Automatic Payment Plan through iTax.
However, there is a critical condition:
The entire qualifying principal tax under the payment arrangement must be fully cleared by 31 December 2026.
Simply entering into a payment plan is therefore not enough. The agreed principal must actually be paid within the amnesty period.
What About Unfiled Tax Returns?
The amnesty is also relevant to taxpayers who have unfiled returns for periods up to 31 December 2025.
KRA advises taxpayers with outstanding returns to file them during the amnesty period.
If filing the outstanding return results in no principal tax being payable, the taxpayer may automatically qualify for amnesty on the applicable late-filing penalties.
If the return results in principal tax being payable, the principal amount must be settled in accordance with the amnesty requirements.
This makes the amnesty period a good opportunity to review your iTax account and identify returns that may have been missed in previous years.
What Happens to Tax Liabilities from 2026 Onwards?
This is another important point.
The 2026 Tax Amnesty Programme applies to qualifying liabilities relating to periods up to 31 December 2025.
Tax liabilities, penalties and interest arising from 1 January 2026 onwards do not qualify for this particular amnesty.
Those liabilities remain subject to the normal tax rules and payment obligations.
Therefore, taxpayers should not assume that all penalties currently appearing on their iTax accounts will automatically disappear.
The relevant tax period and nature of the liability must be examined.
Are Customs Duties Covered?
No.
KRA’s guidance specifically states that customs duties administered under the East African Community Customs Management Act (EACCMA) do not qualify for this tax amnesty.
The programme is focused on qualifying interest, penalties and fines imposed under tax laws covered by the relevant provisions of the Tax Procedures Act.
Taxpayers with customs-related liabilities should therefore treat those obligations separately.
What If You Have a Tax Dispute?
A taxpayer who has an ongoing tax dispute may still have options.
KRA’s current guidance states that taxpayers with matters in court or before the Tax Appeals Tribunal (TAT) should consider using the Alternative Dispute Resolution (ADR) framework to settle qualifying principal tax amounts.
Where the applicable conditions are met and the principal tax is settled through the relevant process, the taxpayer may then access the amnesty benefits.
Because disputed tax matters can involve significant legal and financial considerations, taxpayers should obtain appropriate professional advice before making decisions about an objection, appeal, settlement or ADR process.
How Do You Apply for the KRA Tax Amnesty?
The process depends on your particular tax position.
If you have no outstanding principal tax
Where all qualifying principal tax has already been paid, the applicable waiver may be processed automatically through iTax.
If you have outstanding principal tax
If you cannot make a one-off payment, KRA provides for an Automatic Payment Plan through iTax.
The relevant option can be accessed through the taxpayer’s iTax profile under the applicable debt and enforcement/amnesty functionality.
Taxpayers can also seek assistance from a KRA Tax Service Office or a KRA help desk at a Huduma Centre.
What Happens After the Amnesty Is Granted?
Once the qualifying conditions have been met, KRA will update the taxpayer’s ledger to reflect the applicable waiver.
An Amnesty Certificate is also generated through the iTax system.
KRA states that the certificate will be sent to the taxpayer’s registered email address and can also be accessed through the relevant iTax functionality.
Taxpayers should keep this certificate and other relevant documentation as part of their tax records.
What Happens If You Do Nothing Before 31 December 2026?
This is where taxpayers need to be particularly careful.
The amnesty period is scheduled to close on:
31 December 2026
KRA states that interest and penalties on unpaid principal tax or unfiled returns continue to accrue during the amnesty period; they are not simply frozen while taxpayers decide what to do.
If the taxpayer fails to satisfy the applicable conditions by the deadline, the outstanding amounts may remain recoverable and normal enforcement measures may apply.
For taxpayers with significant historical liabilities, leaving the matter until the final days of the programme could therefore create unnecessary pressure.
A Practical Checklist for Taxpayers
If you are unsure whether you qualify, start with a review of your KRA tax position.
Step 1: Log into iTax
Review your current tax ledger and identify outstanding liabilities.
Step 2: Separate Principal Tax from Penalties and Interest
Do not assume that the total amount shown on your ledger is the amount that must ultimately be paid under the amnesty.
Establish:
- What is principal tax?
- What is interest?
- What is a penalty?
- What is a fine?
- Which tax period does each amount relate to?
Step 3: Check the Tax Period
Determine whether the liability relates to a period on or before 31 December 2025.
Liabilities arising from 1 January 2026 onwards do not qualify for this amnesty.
Step 4: Check for Unfiled Returns
Review your iTax account for any outstanding returns.
Where applicable, file the outstanding returns and determine whether they create a principal tax liability.
Step 5: Reconcile Your KRA Ledger
Sometimes the amount appearing on an iTax ledger may require further investigation, particularly where there are missing payments, credits or other discrepancies.
Do not automatically pay a liability without first understanding what it represents.
Step 6: Resolve Any Discrepancies
If you believe that payments are missing, an assessment is incorrect, or your tax position has not been properly reflected, take steps to resolve the issue as early as possible.
Step 7: Settle the Qualifying Principal Tax
Where principal tax is genuinely outstanding, determine whether you can settle it in full or whether an eligible payment arrangement is appropriate.
Step 8: Confirm the Amnesty
After satisfying the applicable conditions, check your iTax account and obtain your Amnesty Certificate.
Why Businesses Should Act Early
For business owners, tax compliance issues can become increasingly complicated when they are left unresolved for several years.
An old liability may involve:
- Multiple tax periods
- Different tax obligations
- Unfiled returns
- Interest calculations
- Late-filing penalties
- Tax assessments
- Missing payment credits
- Objections
- Tax disputes
- Changes in business ownership or management
- Dormant or inactive businesses
The tax amnesty provides an opportunity to bring qualifying historical matters into focus and determine what needs to be done.
Rather than simply looking at the total figure displayed on iTax, taxpayers should understand the composition and history of the liability before deciding how to proceed.
Important: The Amnesty Does Not Mean You Should Ignore Your Current Taxes
The 2026 Tax Amnesty should not be viewed as a general cancellation of tax obligations.
It is specifically targeted at qualifying penalties, interest and fines relating to tax liabilities for periods up to 31 December 2025.
Your current tax obligations remain payable.
Businesses should therefore continue filing returns, paying taxes when due, maintaining proper records and complying with KRA requirements for 2026 and subsequent periods.
Clearing an old liability while allowing new tax obligations to accumulate would simply create another compliance problem.
How Wambui Kiarie & Associates Can Help
Understanding your KRA ledger is not always straightforward.
A taxpayer may see a large amount on iTax without immediately knowing whether the amount represents principal tax, interest, penalties, fines, unfiled returns or a combination of several issues.
At Wambui Kiarie & Associates, we help businesses and individuals understand their tax position, identify outstanding compliance issues and determine the appropriate steps for resolving qualifying tax liabilities.
Our tax and advisory support can include:
- Review of KRA iTax tax ledgers
- Tax compliance reviews
- Identification of outstanding returns
- Tax reconciliation
- Review of penalties and interest
- Assessment of tax liabilities
- Assistance with tax regularisation
- Guidance on qualifying tax amnesty matters
- Payment-plan guidance
- Tax dispute and ADR support
- Ongoing tax compliance advisory
If you have an old KRA tax liability, do not wait until the 31 December 2026 deadline to find out whether you qualify.
A proper review of your tax position can help you understand what you owe, what may qualify for relief and what action needs to be taken before the amnesty window closes.
Need Help Reviewing Your KRA Tax Position?
Contact Wambui Kiarie & Associates for professional tax, audit and advisory support.
Audit | Tax | Advisory
Disclaimer: This article is intended for general information and does not constitute individual tax or legal advice. Eligibility for the KRA Tax Amnesty depends on the taxpayer’s specific circumstances, tax records and the applicable law and KRA procedures. Taxpayers should obtain professional advice where their circumstances involve disputed assessments, significant liabilities or complex tax matters.
Source: Kenya Revenue Authority — 2026 Tax Amnesty Programme and related public notices.